Why Investing in Real Estate Appeals to Military Families Facing Frequent Relocation
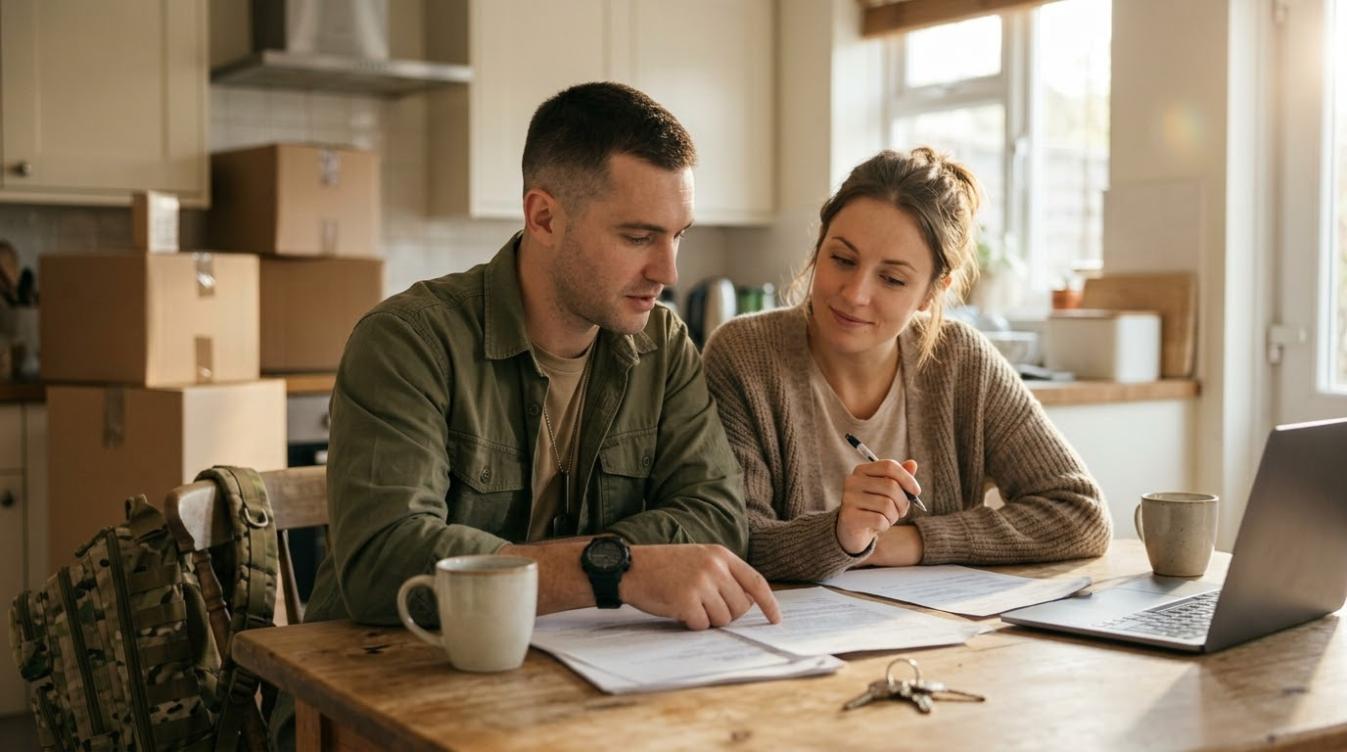
Few careers move people as often as military service. Orders arrive, boxes get packed, and a family that has just settled into a community may be starting over somewhere new within a couple of years.
For many of these households, investing in real estate (Investeren In Vastgoed) offers something rare in that lifestyle: an asset that stays in place while everything else moves. The idea says a lot about how service families think about stability, income, and long-term planning.
Stability in a Life Defined by Movement
Military families often describe the hardest part of relocation as the loss of permanence. Friends, schools, and routines reset with every posting.
It can feel as though no place ever fully belongs to the family. Property ownership provides a fixed point on the map, a place that stays theirs regardless of where the next assignment lands.
That emotional anchor matters, even before any financial return enters the picture. It often shapes the first decision to buy.
Turning Each Posting Into an Opportunity
A home purchased at one duty station does not have to be sold when orders change. Many families keep the property and rent it out, converting a former residence into a source of monthly income.
Fellow service members arriving at the same base often create steady rental demand, which helps reduce vacancy risk. Over several postings, a family can build a small portfolio simply by repeating the same pattern.
Each move adds a property rather than closing a chapter.
Predictable Income Supports Planning
Military pay is structured and predictable, which lenders and planners tend to view favorably. Many governments also provide housing support to service members, and those payments can free up other income for mortgage obligations or savings.
Rules differ widely between countries and change over time, so families should confirm the current terms that apply to them.
Predictable pay makes the numbers easier to model before committing to a purchase. It also makes monthly budgeting far less stressful.
Equity Builds Quietly Over a Long Career
Real estate rewards patience. Mortgage payments gradually shift from interest toward principal, and property values often rise over long periods, though rarely in a straight line.
A service career of twenty years or more gives families a long runway for that process. By retirement, equity gathered across several postings can form a meaningful part of their financial foundation, alongside pensions and other savings.
Choosing Where to Buy
Location decisions look different for families who do not control where they live. Some buy near the current base for convenience and strong rental demand from other service members.
Others buy in a hometown or a planned retirement destination, treating the purchase as a future home rather than a temporary one.
Neither approach is universally better. The right choice depends on risk tolerance, local market conditions, and how long the family expects to hold the property.
Managing Property From a Distance
Distance is the practical challenge. A landlord living thousands of kilometers away cannot fix a leaking roof personally.
Many military investors hire professional property managers who handle tenants, repairs, and paperwork in exchange for a share of the rent. That fee reduces returns, but it protects time and peace of mind during deployments, when a family may be hard to reach for months at a stretch.
The Learning Curve for First-Time Investors
First-time investors face a steep learning curve. Reading leases, understanding local tenant laws, and estimating maintenance costs all take time, and mistakes can be expensive.
Military communities often help here. Spouses, veterans, and housing offices frequently share advice, and many families learn from neighbors who have already walked the same path.
Starting with a single, modest property lets newcomers learn before they expand.
Risks Worth Weighing
Real estate is not a guaranteed win. Vacancies interrupt income, repairs can be costly, and markets can decline just when a family needs to sell.
Borrowing amplifies both gains and losses. Individual circumstances vary enormously, so anyone considering this path benefits from speaking with a qualified financial advisor and reviewing local rules before signing anything.
The Role of Public Policy
Housing decisions never happen in a policy vacuum. Tax treatment of rental income, lending rules, and service-member protections all shape what a property investment can realistically deliver.
Coverage on how government functions in society offers useful background on why those rules exist and why they shift as public priorities change.
Families who follow policy developments tend to spot opportunities and risks earlier than those who do not.
A Strategy Built for Mobility
Property appeals to relocating families for a simple reason: it is something they can own that does not need to move. Stability, rental income, equity, and long-term planning all work together when approached with realistic expectations.
For service families willing to do the homework, real estate can turn a life of constant motion into a more secure financial future.